How Enterprise AI Agents Automate Dubai Financial Service Workflows
October 08, 2026
Ayush Kanodia
Enterprise AI agents are moving financial automation beyond isolated tasks. Instead of simply extracting information or following fixed rules, an AI agent can retrieve data, evaluate context, trigger actions across enterprise systems, route exceptions and maintain an audit trail.
For Dubai financial institutions, this distinction matters. KYC, transaction monitoring, invoice processing, regulatory reporting and customer operations involve multiple systems, manual handoffs and strict governance requirements. Working with an AI development company in UAE can help financial organizations design agentic workflows that integrate with existing systems while keeping high-impact decisions under appropriate human oversight.
The opportunity is significant, but implementation must account for CBUAE requirements, DIFC considerations, data privacy, explainability, access controls and operational resilience.
What Are Enterprise AI Agents in Financial Services?
An enterprise AI agent is software that can interpret a business objective, retrieve relevant information, use approved tools and execute multiple steps within a defined workflow. That makes it different from both traditional automation and an AI assistant.
AI Automation vs. AI Assistants vs. AI Agents
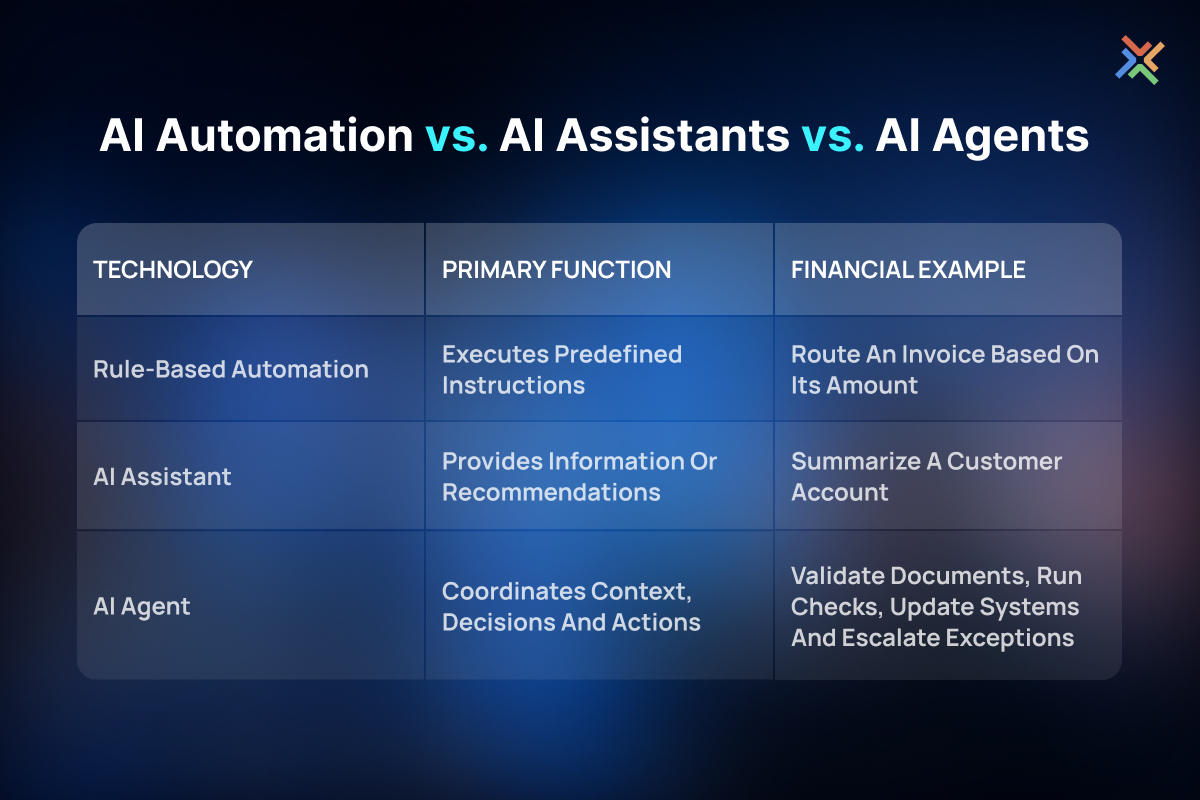
The distinction is important because financial workflows rarely consist of one task. A customer onboarding process, for example, may involve document collection, identity verification, screening, data entry, risk assessment and compliance review. An AI agent can coordinate those steps instead of automating only one part of them.
Why Dubai Financial Institutions Are Moving Beyond Traditional Automation
AI adoption in UAE finance is rising. Having AI plans does not mean the technology is being used at scale.
KPMG’s research in the UAE shows that 49% of finance organizations have AI plans and 59% are running or planning AI pilots. Only 37% of finance leaders in the UAE say they are seeing positive returns from their AI efforts. This gap shows a problem: getting AI from pilot stage to real day-to-day operations is hard.
At the time Dubai’s financial sector is moving fast to support AI. In April 2026 the Dubai International Financial Centre said it wants to become the world’s AI-native financial centre. That means AI will be built into its laws, business rules, talent training and the whole financial eosystem.
For banks and financial firms this shift means one thing: AI must fit into operations. It cannot just be a tool sitting outside the main workflow. It has to work inside the system not alongside it.
5 Financial Workflows Enterprise AI Agents Can Automate
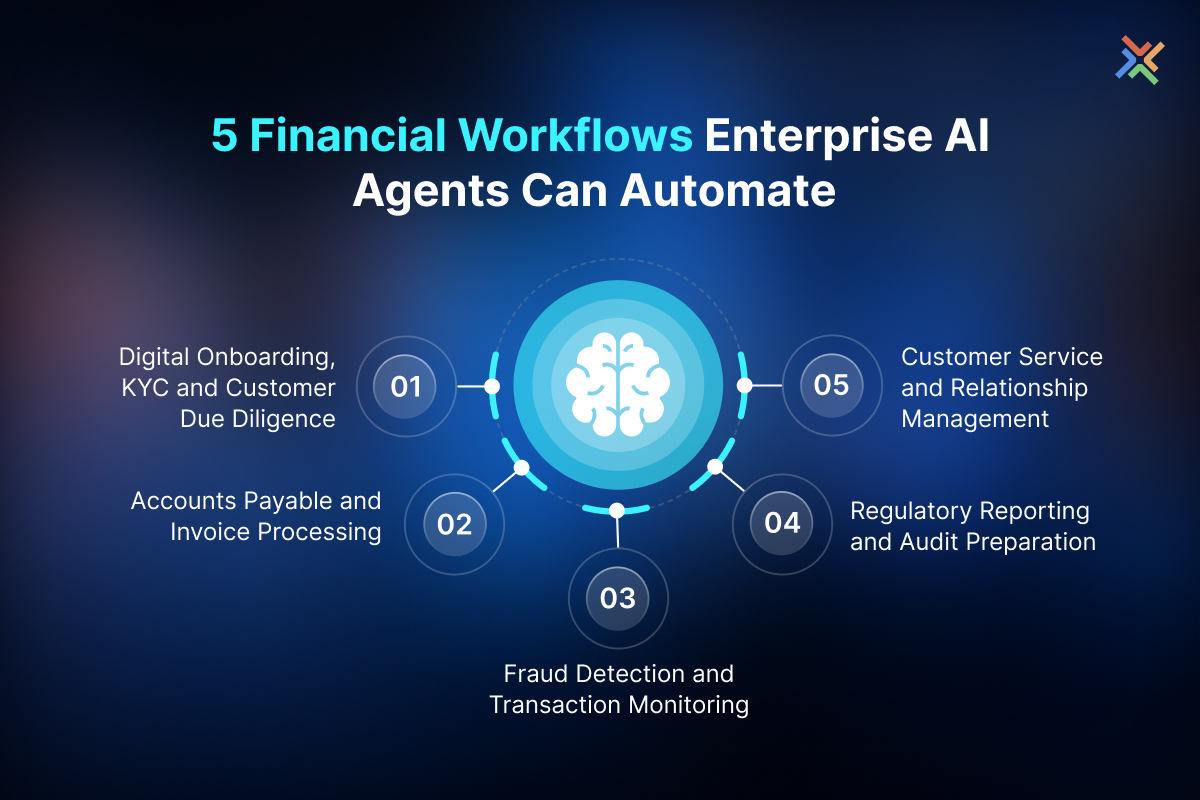
These workflows show where AI agents can reduce manual coordination while keeping regulated decisions within defined controls.
1. Digital Onboarding, KYC and Customer Due Diligence
Customer onboarding involves large volumes of documents and repetitive verification steps.
An AI agent can coordinate a workflow such as:
Document intake → data extraction → identity validation → screening → missing-information detection → risk-based routing → human review → record creation.
For example, an agent can extract information from an Emirates ID or passport, compare fields across submitted documents, identify inconsistencies and route incomplete applications to the appropriate team.
The important boundary is decision authority. The agent can automate information gathering, validation and workflow coordination, while high-impact customer decisions remain subject to the institution's approved controls.
This aligns with CBUAE's 2026 guidance, which specifically addresses transparency, accountability, explainability, data privacy, fairness and governance when licensed financial institutions use AI and machine learning.
2. Accounts Payable and Invoice Processing
Finance departments often receive invoices through email, PDFs, portals and other channels. Processing them manually creates multiple handoffs between procurement, finance and approvers.
An AI agent can:
- Read and classify incoming invoices
- Extract supplier and line-item information
- Match invoices against purchase orders
- Identify duplicate or inconsistent records
- Check approval thresholds
- Route exceptions
- Update approved records in an ERP
- Maintain the workflow history
PwC reports that AI-driven invoice extraction and purchase-order matching can reduce procure-to-pay cycle times by up to 80% in applicable workflows. That is a PwC benchmark, not a universal result; actual performance depends on process design, data quality, integrations and exception volumes.
The more useful enterprise metric is therefore not simply "hours saved." It is the percentage of invoices processed without manual intervention while maintaining financial controls.
3. Fraud Detection and Transaction Monitoring
Fraud monitoring requires continuous analysis of transaction activity, customer context and risk signals.
An agentic workflow can sit around specialized fraud and anomaly-detection models:
Transaction event → risk analysis → contextual data retrieval → anomaly assessment → case creation → analyst escalation → investigation record.
The agent does not need to replace an existing fraud model. Instead, it can coordinate what happens before and after the model produces a result.
For example, a suspicious transaction could automatically create a case, retrieve relevant customer and transaction history, summarize the available evidence and route it to an investigator.
CBUAE's AI guidance also states that licensed financial institutions should consider using AI to identify potential fraud, criminal activity, AML disparities and suspicious activity through trends and patterns, subject to applicable legal and regulatory requirements.
4. Regulatory Reporting and Audit Preparation
Regulatory reporting often requires information to be gathered from multiple systems, reconciled, validated and reviewed before submission.
An AI agent can coordinate:
Data collection → reconciliation → validation → exception detection → report preparation → evidence collection → human review.
This can reduce the manual work involved in assembling reporting packages without turning regulatory reporting into an uncontrolled autonomous process.
The audit layer is equally important. Every relevant action should be traceable: which data was retrieved, which model or rule was used, what action occurred, what exception was detected and when a human intervened.
5. Customer Service and Relationship Management
Financial institutions also have large volumes of operational requests that do not require a senior employee to perform every step manually.
AI agents can classify requests, retrieve approved information, summarize customer histories, prepare relationship-manager briefs, route service cases and draft responses.
For bilingual environments, workflows can also be designed to handle Arabic and English interactions. CBUAE's 2026 AI guidance specifically addresses understandable disclosures in both Arabic and English where applicable.
The objective is not to make every customer interaction autonomous. It is to remove repetitive coordination work so employees can focus on cases requiring judgment.
How an AI Agent Executes a Financial Workflow
A production financial-services agent can be understood as a six-stage execution loop.
- Observe: Detects an event such as an application, transaction, invoice, or customer request.
- Retrieve: Pulls authorised data from CRM, ERP, databases, documents, and knowledge bases.
- Reason: Evaluates information against business rules, policies, models, and workflow instructions.
- Act: Uses approved APIs or tools to update records, create cases, route approvals, or trigger actions.
- Escalate: Sends exceptions, high-risk cases, or decisions outside its authority to a human.
- Log: Records actions, exceptions, decisions, and human interventions for monitoring and auditability.
Where Human Oversight Still Matters
Financial institutions should distinguish between tasks that are suitable for controlled autonomous execution and decisions that require human accountability.
AI agents can generally support lower-risk activities such as document extraction, classification, reconciliation, information retrieval, case routing, report drafting and workflow coordination.
Human approval may be appropriate for high-impact customer decisions, unusual compliance cases, material financial actions, suspicious-activity investigations and irreversible transactions.
CBUAE's 2026 guidance places responsibility for AI systems and outcomes with senior management and boards of licensed financial institutions. It also expects appropriate governance, monitoring and oversight.
The practical principle is simple: give the agent enough authority to remove operational friction, but not more authority than the institution can govern.
AI Agent Architecture for Dubai Financial Services
A financial-services AI agent typically requires more than an LLM.
Data and Integration Layer
This connects the agent to:
- Core banking and transaction systems
- CRM and ERP platforms
- Payment systems
- Document repositories
- Data warehouses
- Internal APIs
- Event streams
Integration is critical because an agent that cannot safely access or update enterprise systems remains an assistant rather than an operational agent.
Intelligence and Agent Layer
This can include:
- Large language models
- Machine-learning models
- Retrieval-Augmented Generation
- Tool calling
- Workflow orchestration
- Specialized risk or anomaly models
Different components should perform different jobs. A general-purpose LLM, for example, should not automatically become the institution's fraud-detection engine.
Governance Layer
The governance layer defines what the agent can access and do. Controls can include role-based permissions, approval thresholds, business rules, data policies, audit logging, monitoring and override mechanisms.
Human-Review Layer
Employees need clear interfaces for reviewing exceptions, approving sensitive actions and understanding why an agent took a particular workflow path.
WDCS Technology's AI development approach includes requirements assessment, scope definition, technology selection, data preparation, model assessment, integration, testing, deployment and ongoing maintenance. Its AI development services UAE also cover generative AI, machine learning, NLP, RPA, business intelligence and system integration.
Dubai and UAE Compliance Considerations
AI automation in financial services cannot be separated from governance.
CBUAE-Regulated Institutions
CBUAE issued its Guidance Note on the Consumer Protection and Responsible Adoption and Use of AI and ML by Licensed Financial Institutions in February 2026.
The guidance covers governance and accountability, fairness and non-discrimination, transparency and explainability, data quality, privacy and security, continuous monitoring and third-party risk.
It also states that financial institutions should maintain appropriate governance over AI systems and should not employ AI models that they have no control over.
DIFC and DFSA-Regulated Businesses
DIFC's regulatory environment has its own requirements. In June 2026, DIFC launched consultation on amendments to its Data Protection Regulations addressing AI-native systems, safety and the role of an Autonomous Systems Officer.
This means a Dubai financial institution should identify the applicable regulatory perimeter before designing the agent architecture.
Data, Access and Auditability
A production implementation should consider:
- Least-privilege access
- Data classification
- Privacy-by-design
- Security-by-design
- Action-level logging
- Model and workflow monitoring
- Human approval thresholds
- Failure handling
- Rollback or override mechanisms
- Third-party AI risk
These controls should be designed before deployment rather than added after the first production incident.
AI Implementation Roadmap for Financial Institutions
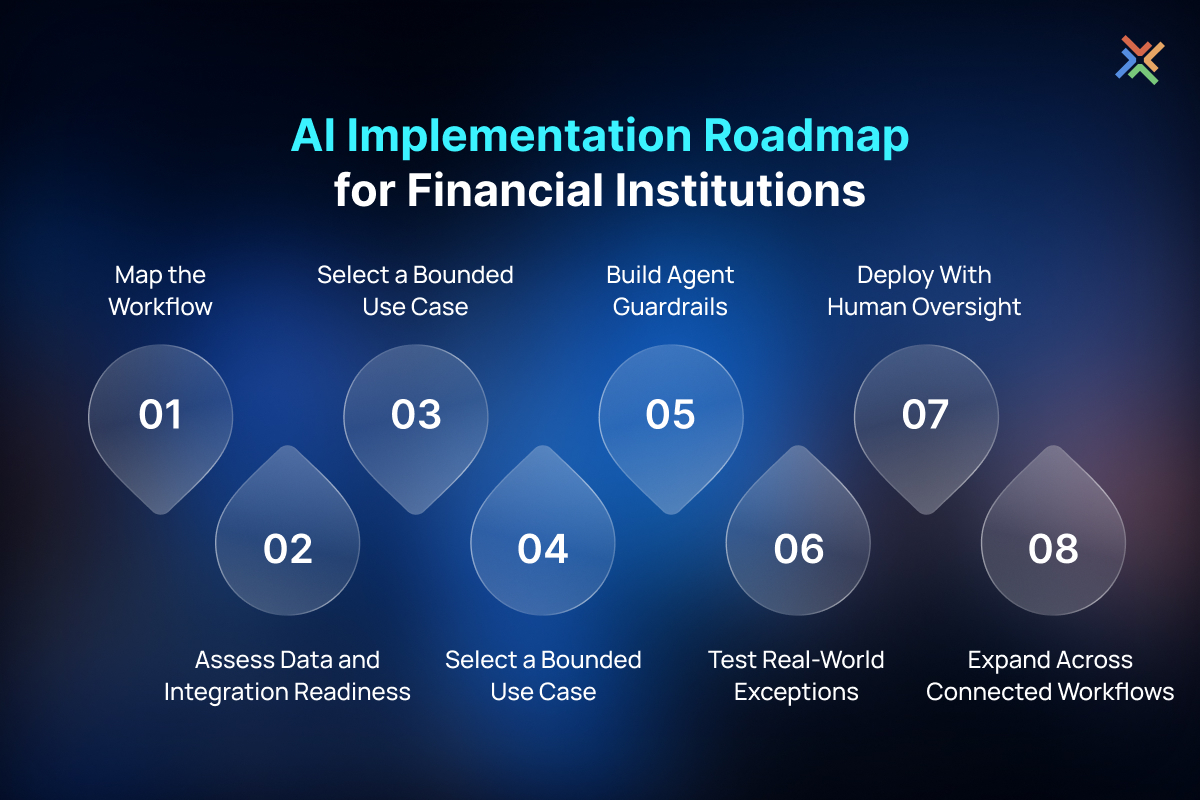
A structured roadmap helps financial institutions move from a defined use case to governed, scalable AI agent deployment.
Step 1: Map the Workflow
Document every manual handoff, system dependency, exception and approval point.
Step 2: Assess Data and Integration Readiness
Check whether the required data is accessible, reliable and sufficiently structured. Identify API availability and legacy-system constraints.
Step 3: Select a Bounded Use Case
Choose a workflow with measurable outcomes and clearly defined authority boundaries.
Step 4: Build Guardrails Into the Agent
Define its tools, permissions, business rules, escalation conditions and logging requirements.
Step 5: Test Real Exceptions
Do not test only successful scenarios. Test missing documents, conflicting records, unusual transactions, system outages and bilingual inputs.
Step 6: Deploy With Human Oversight
Start with controlled production monitoring and establish clear ownership for failures and exceptions.
Step 7: Expand Across Connected Workflows
Once one workflow performs reliably, connect adjacent processes rather than deploying disconnected agents across the organization.
What to Measure After Deployment
The right KPI framework depends on the workflow, but financial institutions can track:
- Workflow cycle time
- Straight-through processing rate
- Manual touches per case
- Exception rate
- Escalation rate
- False-positive rate
- Document-processing accuracy
- SLA adherence
- Audit preparation time
- Cost per processed case
- Agent/tool failure rate
- Human intervention rate
These metrics make it possible to distinguish an AI demonstration from an operational improvement.
Build Enterprise AI Agents for Financial Workflows
For Dubai financial institutions, the business case for AI agents is less about adding another AI interface and more about redesigning how work moves between people, data and enterprise systems.
The strongest starting point is a specific workflow: identify where employees spend time collecting information, reconciling records, routing cases or preparing reports; establish what the agent can safely execute; define where humans must intervene; then connect the workflow to the systems that already run the business.
WDCS Technology UAE can help organizations assess AI opportunities, select appropriate technologies, integrate AI into existing infrastructure and take solutions through testing, deployment and ongoing support.
Discuss your AI Workflow With WDCS Technology UAE.
Automate Your High-Value Financial Workflows With AI Agents
Turn manual KYC, compliance, reporting, finance and customer workflows into governed AI-powered operations. WDCS Technology UAE can help you identify the right use case, integrate AI agents with your existing systems and deploy them with the controls your financial environment requires.